The Federal Reserve's September decision might be a close call, but traders are betting that policymakers will raise the federal funds rate, a target range for short-term interest rates, for the first time in more than three years.
Though President Donald Trump and some in his administration called for lower rates, economists believe a cut probably isn't on the table. Instead, they said, the Fed's decision is whether to hike or hold.
Fed policymakers typically raise the benchmark for short-term interest rates across the country to tame inflation and lower it to stimulate the job market. So far in 2026, they have chosen to leave it unchanged at a range of 3.5% to 3.75%.
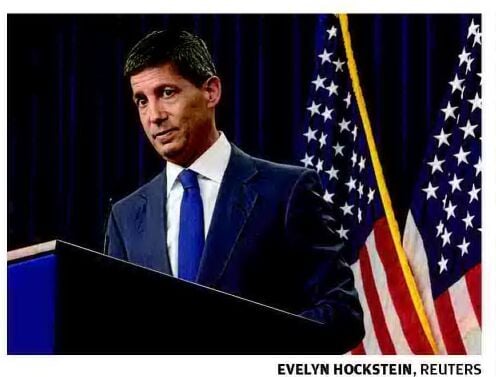
Ahead of the September meeting, inflation rose faster than workers' paychecks and hiring rebounded, with U.S. employers adding 162,000 jobs in August. Fed Chair Kevin Warsh described the labor market on Aug. 28 as "stable" and said policymakers should be focused on rising prices.
"Price stability is not self-executing," Warsh said. "It is the Fed's job to deliver stable prices."
As of Sunday, most traders, according to CME FedWatch, bet the Federal Open Market Committee will raise the federal funds rate by a quarter-point on Wednesday. While traders were more divided on what the committee will do at its final two meetings this year, a little more than half predicted that it would leave the range at 3.75% to 4% in October, and slightly fewer than half think it will raise it to 4% to 4.25% in December.
Fed watchers will soon get more clarity on where officials believe the federal funds rate is headed as the September decision is expected to be released alongside the FOMC's Summary of Economic Projections. That quarterly report includes committee members' projections for the appropriate path for interest rates. No fan of letting markets know what he's thinking, Warsh did not provide his own projections in June, but his colleagues did.
Rising inflation
While year-over-year consumer price inflation is down since peaking at 9.1% in 2022, it stood at 3.4% in August, still above the Fed's 2% annual target.
Several factors are behind its stubbornness. Aside from post-pandemic sticker shock that never went away, the Iran war, tariffs and the AI build out contribute to the rise in prices for American consumers at the gas pump, grocery store and almost everywhere else.
After Labor Department data on Sept. 11 showed consumer costs rose again in August, several experts said the new numbers would likely be enough to push the Fed to raise the target range at its next meeting. Analysts from Bank of America Global Research, KPMG Economics and Oxford Economics noted that while a hike is not guaranteed, the data strengthened the case for an increase.
"Will their broad reading of economic conditions remain sufficiently benign for them to hold steady for now or will the moderate reacceleration in inflation represent a tipping point that nudges them to hike? That's the question," Jim Baird, Plante Moran Financial Advisors chief investment officer, said in a note to USA TODAY. "If policymakers choose to stand pat again, the questions surrounding what they're waiting for will become louder and more direct."
Close call
Despite stubborn inflation, a September rate hike is not a "slam dunk," according to Mike Skordeles, Truist Advisory Services' head of U.S. economics.
While gas prices were not the only thing that got more expensive last month, their 3.9% increase helped drive August's rise in consumer inflation. Fed policymakers historically tended to look through supply shocks, such as those stemming from constrained oil supply linked to the Middle East conflict and the Russia-Ukraine war, because they cannot directly control them. However, they tend to be more likely to respond when those supply shocks start raising the cost of other things.
In addition, markets already pushed long-term rates higher. At the Fed's last meeting in July, Warsh suggested that markets may be doing some of the FOMC's inflation-fighting work for it, pointing to higher nominal and real yields across the Treasury curve.
"The hike-hold debate is rather close," Skordeles said. "There are a lot of reasons to go in either direction."
Last rate change
In 2024 and 2025, the Fed followed a similar pattern. In both years, the Federal Open Market Committee left the target range alone until voting to change it in September and at its two meetings that followed. What's different is that back then, the FOMC lowered the range. Now, it's contemplating raising it.
If committee members were to approve a hike, it would be the first time they opted to do so since July 2023. At that time, U.S. employers added an estimated 209,000 jobs and year-over-year consumer price inflation stood at 3% the month before.
While the committee has left the federal funds rate unchanged this year, three of its 12 voting members dissented from that decision at its most recent meeting.
In general, the Fed raising its benchmark rate can lead to higher interest rates on credit cards, auto loans, and personal loans for borrowers. For savers, it typically means higher returns on their high-yield savings accounts and certificates of deposit.